The check you actually take home from a California truck accident settlement is the gross amount minus the attorney fee (commonly 33% to 40%), minus case costs, minus medical liens, and state law caps those liens. A private health plan with a lien cannot recover more than one-third of the settlement if you had a lawyer (Civil Code §3040). A hospital lien is limited to 50% of what is due you (§3045.4). Medi-Cal’s lien is cut 25% and can never exceed your net (W&I §§14124.72, 14124.78). Medicare shares the cost of the fee (42 CFR 411.37).
Everybody asks about the lawyer’s cut. That’s the easy part, because it’s in writing before you sign. What blindsides people is what comes out after it: the case costs the firm fronted, and the medical bills that hospitals, health plans, Medicare, and Medi-Cal want paid back. One Texas claimant posted a breakdown in September 2026: a $42,500 settlement, a 40% fee of $17,000, $4,239.47 in costs, and roughly $20,000 in medical balances, leaving $1,077.80. That’s one person’s account, not a statistic, but it shows why the lien math matters as much as the fee. Below, we run California’s actual lien statutes through worked examples so you can see where the money goes in a big rig accident settlement.
The deduction order: fee, costs, then liens
Every settlement statement runs top to bottom in the same order. The attorney fee is figured on the gross. Case costs the firm advanced come out next. Liens get paid from what’s left, and you get the rest.
| Step | What comes out | Governing rule |
|---|---|---|
| 1. Attorney fee | Percentage of the gross — commonly 33% pre-suit, often 40% after filing | Written agreement required, Bus. & Prof. Code §6147 |
| 2. Case costs | Filing fees, records, experts, depositions advanced by the firm | Must be explained in the fee agreement (§6147) |
| 3. Medical liens | Health plan, Medicare, Medi-Cal, hospital, or provider liens | Civ. Code §§3040, 3045.4; W&I §§14124.72, .78; 42 CFR 411.37 |
| 4. Net to you | Whatever remains | — |
The 33%–40% range is typical practice, not a statewide survey. No public dataset of California fee rates exists. Before you sign, pin down your fee and whether it steps up if a lawsuit gets filed. Our guide on what to ask a truck accident lawyer about fees covers the questions.
California caps what lienholders can take back
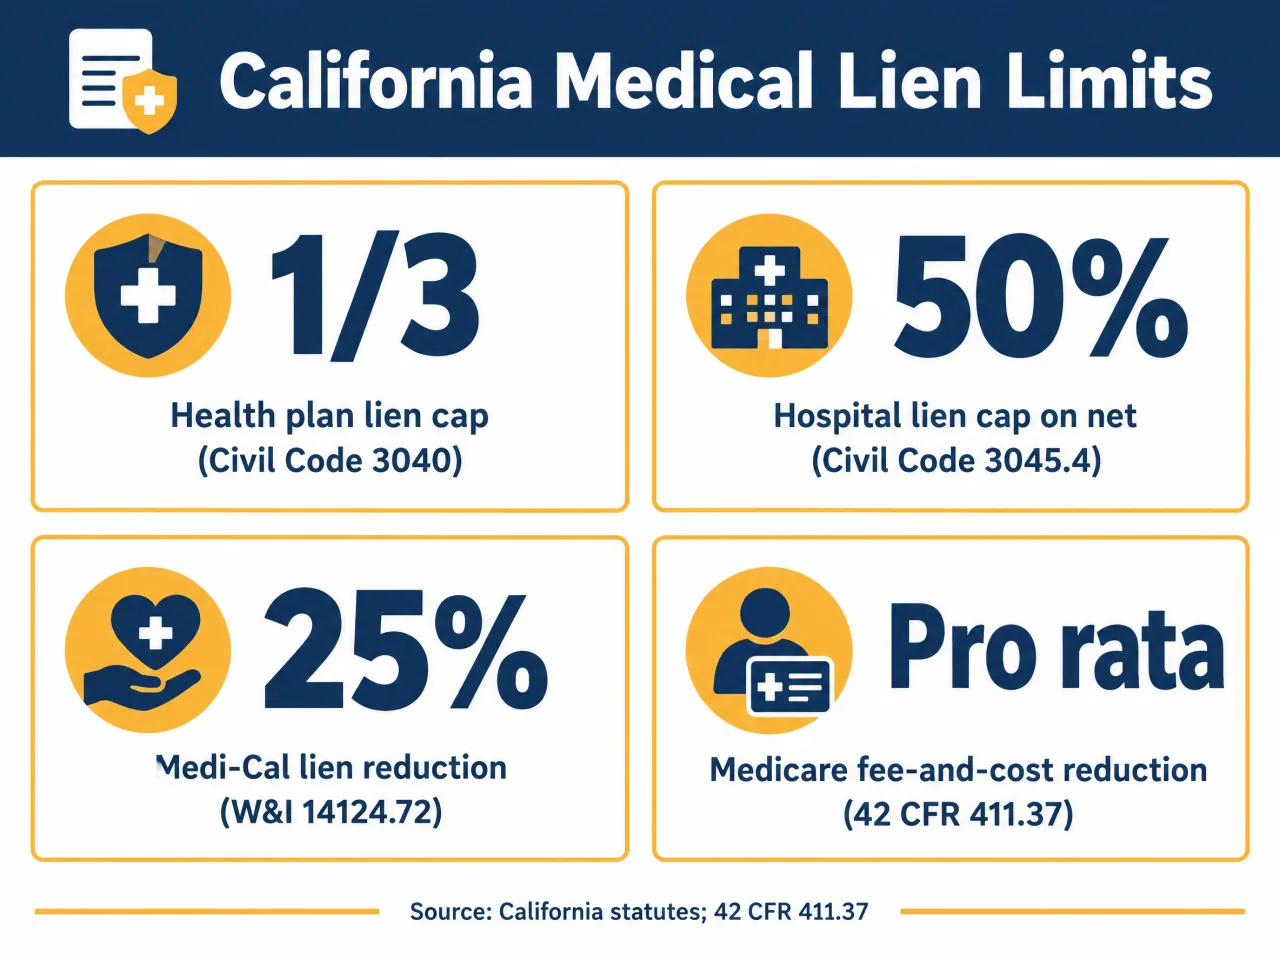
Here’s the part most people never hear about. Four rules limit how much of your medical bills have to be paid back out of the settlement, and which one applies depends on who paid for your care.
| Lienholder | Limit | Source |
|---|---|---|
| Private health plan / HMO | No more than 1/3 of the settlement if you had a lawyer (1/2 if not), reduced pro rata for fees and costs | Cal. Civ. Code §3040 |
| Hospital (emergency care lien) | Only out of 50% of money due you, after prior liens | Cal. Civ. Code §3045.4 |
| Medi-Cal | Reduced 25% for attorney fees plus a pro-rata share of costs; never more than your net | W&I §§14124.72(d), 14124.78 |
| Medicare | Reduced by the ratio of fees and costs to the settlement | 42 CFR 411.37(c)–(d) |
These are ceilings set by statute, not the final word. Lienholders can and often do take less in negotiation, and a lawyer who works the liens can move your net as much as the gross. Some liens play by different rules and fall outside these caps: ERISA self-funded plans, workers’ compensation (which matters if you were hurt driving for work), and providers treating on a lien.
Worked examples: net to you at five settlement sizes
Same hypothetical settlement, run through each statute. Each column assumes one lienholder holds the entire medical balance and nobody negotiated below the statute. These are illustrations of the formulas, not reported case results.
| Gross | Fee | Costs | Medical | No reduction | Health plan | Medicare | Medi-Cal | Hospital |
|---|---|---|---|---|---|---|---|---|
| $10,000 | 33.3% | $500 | $4,000 | $2,167 | $4,111 | $3,700 | $3,167 | $3,083 |
| $25,000 | 33.3% | $1,500 | $8,000 | $7,167 | $10,313 | $10,313 | $9,167 | $7,583 |
| $50,000 | 40% | $4,000 | $20,000 | $6,000 | $17,333 | $15,600 | $11,000 | $13,000 |
| $100,000 | 40% | $8,000 | $35,000 | $17,000 | $34,667 | $33,800 | $25,750 | $26,000 |
| $750,000 | 40% | $60,000 | $200,000 | $190,000 | $286,000 | $286,000 | $240,000 | $195,000 |
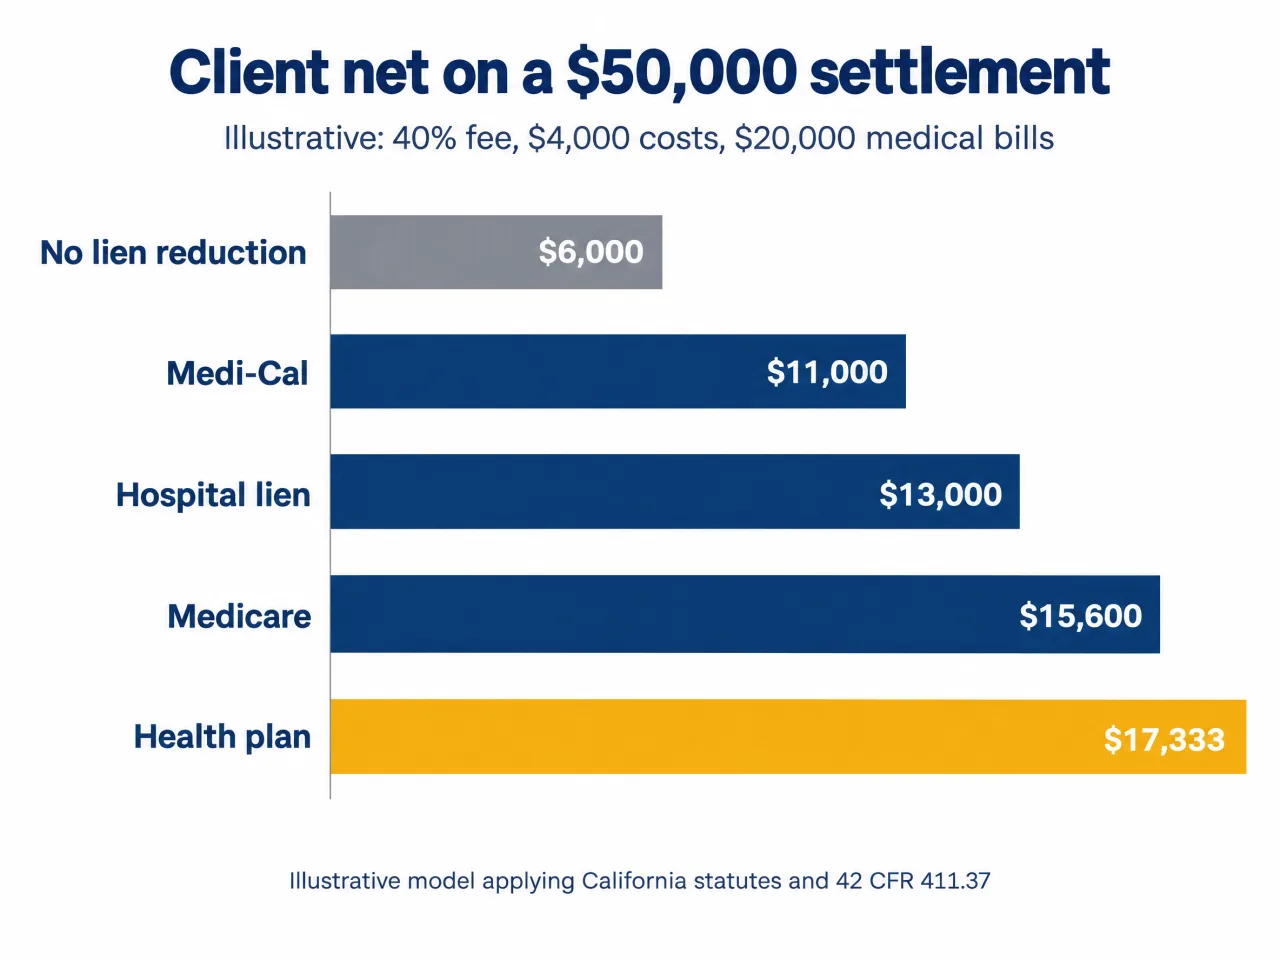
Take the $50,000 row. Pay the full $20,000 in medical bills and you walk away with $6,000. Apply the statutes and the net climbs to between $11,000 and $17,333, depending on who holds the lien. The spread is widest in the middle, where medical bills eat a big share of the settlement. At the top end, with catastrophic injuries and a carrier’s policy in play, the fee and costs are the big numbers, which is why documenting future care and lost earning capacity matters more than any lien reduction.
Estimate your own net
Plug in your own numbers. The calculator runs the same formulas as the table above.
- Attorney fee
- $20,000
- Case costs
- $4,000
- Lien repaid
- $8,667
- Estimated net to you
- $17,333 (35% of gross)
- Net with no statutory reduction
- $6,000
Illustrative only. Assumes one lienholder holds the whole medical balance and applies only the statutory formula — no negotiated reduction. Actual liens, fee agreements, and costs vary; ask your attorney for a written settlement statement.
Why truck cases change the math
A truck case isn’t a car case with a bigger vehicle. Two differences hit your net. First, there’s more coverage: federal rules require interstate freight carriers to carry at least $750,000, and many carry more, so a small policy is less likely to cap the gross. Second, these cases cost more to win. Accident reconstruction, trucking-safety experts, and black box (ECM) downloads are all case costs, and a filed truck lawsuit typically triggers the higher fee tier. On the other side of the ledger, more defendants (the carrier, trailer owner, broker, or shipper identified under truck accident liability rules) can raise the gross enough to outweigh those costs.
Time is part of the cost
Industry data reported from the Insurance Research Council’s 2017–2022 claims database (7.4 million auto injury claims) shows the share of claimants with attorneys rose from 40% to nearly 50%, litigation rose from 10% to 18% of claimants, and represented bodily-injury claims took a median of roughly 440 days to close, more than twice as long as unrepresented claims. The full report is available only to IRC members, so these figures are cited as reported. Waiting until you’ve reached maximum medical improvement is usually worth it, because settling early can leave future care unpaid. It’s also why your state’s filing deadline should be tracked from day one: two years in California, and anywhere from roughly one to six years elsewhere (deadlines by state). Our filing deadline calculator gives the date.
Five questions to ask before you sign a settlement statement
- Is the fee calculated on the gross, and did it step up because suit was filed?
- What are the itemized case costs, and were any charged at a markup?
- Which liens are statutory (health plan, hospital, Medi-Cal, Medicare), and was each statutory reduction applied?
- Did anyone negotiate the liens below the statutory ceiling?
- Are any providers treating on a lien, and what did they agree to accept?
Haven’t settled yet? If you want these questions answered by a truck attorney licensed in the state where your crash happened, start a free case review. The lien caps above are California’s. Other states set their own lien rules, and an attorney there can apply them.
Methodology
Researched September 23, 2026. Lien limits are taken from the current text of California Civil Code §§3040 and 3045.4, Welfare & Institutions Code §§14124.72 and 14124.78, and 42 CFR 411.37. Worked examples use hypothetical inputs and apply one lienholder’s formula to the entire medical balance; the health-plan column applies the one-third cap and then the pro-rata fee-and-cost reduction. Claims-duration figures are from the Insurance Research Council as reported in secondary coverage. Reddit breakdowns are user-reported and shown as examples only. Excluded for lack of a primary source: the commonly repeated claims that injured people “keep 60%–70%” of a settlement and that represented claimants net less per dollar of medical bills. This page is general information, not legal or tax advice; your lien amounts depend on your policies and treatment.
Sources
- 42 CFR § 411.37 — Amount of Medicare recovery when a primary payment is made as a result of a judgment or settlement — Cornell LII / eCFR
- California Civil Code § 3040 — Health care plan liens — FindLaw
- California Civil Code § 3045.4 — Hospital liens — FindLaw
- California Welfare & Institutions Code § 14124.72 — Medi-Cal lien reduction — FindLaw
- California Welfare & Institutions Code § 14124.78 — Medi-Cal recovery ceiling — Justia
- California Business & Professions Code § 6147 — Contingency fee contracts — California Legislative Information
- Auto Injury Insurance Claims: A Study of Increasing Claim Severity — Insurance Research Council
- “$42.5k car accident settlement, attorney/medical bills leave me with $1,077” — r/Insurance (Reddit)
Federal regulations and crash statistics are updated periodically. Figures cited on this page reflect the referenced publications at the time of writing; check the source for the current edition.